News › Derivatives
Derivatives
Bitcoin's biggest options bet is now a fall below $60,000, not a rally to $100,000
On Deribit the $60,000 put holds $900M of open interest, ahead of the $100,000 call at $867M; Volmex implied volatility hit 57.13 on Sunday, its highest since June.
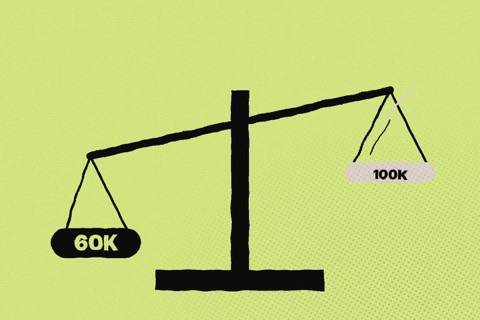
For the first time in months, the most popular bet in bitcoin options is on a decline. According to CoinDesk, citing Deribit data, the $60,000 put now has about $900 million in notional open interest. It overtook the $100,000 call, which holds $867 million.
How it happened matters. Paradigm's Nicolas Quatravaux told CoinDesk that the $100,000 call lost the top spot mainly because traders sold upside bets, not because they rushed into puts. More than 12,000 BTC of those calls were bought in September, when bitcoin had rallied from about $64,000 to over $85,000 during August and September, and about 6,700 BTC were sold back in October. The $60,000 put, he said, had been the go-to protection strike all year, with heavy buying during wobbles in February and March and again in June. He also cautioned that open interest reflects positioning built up over months: "OI is a stock, not a flow."
There is also fresh activity. On Paradigm, one large player rolled a big put position down as prices fell, from the $74,000 strike in late October to $63,000 by the end of November, in what CoinDesk describes as more than $1 billion of put blocks in two days. SignalPlus reported a put ratio backspread on Friday: 750 BTC of $68,000 puts bought and 500 BTC of $72,000 puts sold, expiring 27 November, with break-evens at about $62,380 and $70,650.
Volatility rose with it. Volmex's 30-day implied volatility index, BVIV, climbed to 57.13 on Sunday, its highest since June, before easing to 44. Founder Cole Kennelly linked the unease to exchange security concerns, AI-related market uncertainty and a tougher regulatory outlook.
The same day, market maker Wintermute published a note saying bitcoin could slide into the $50,000s if it stays below its 200-week average, near $68,000, and named the $60,000 put cluster as the next target after the weekend low of $62,000. It cites rate-hike odds of about 92% for December, a 10-year Treasury yield back above 5%, about $1.9 billion of net ETF outflows so far in 2026 against $21 billion of inflows in 2025, shrinking stablecoin supply and drying treasury-company demand.
What it does not say is that $60,000 will be hit. Options positioning shows where traders want protection or hope for a payout, and a big strike can act as a magnet or as a floor. Wintermute itself says it is not calling bottoms. The conditions it names for turning less cautious are a UTC daily close above $68,000 with same-day ETF inflows, or Fed data that removes a January hike. Treat the $60,000 number as a level the market is watching, not a forecast.
Facts only, never financial advice.